By DAMIAN J. TROISE
NEW YORK (AP) — Inflation updates dominate the calendar this week, along with a checkup on the housing market and more data on employment in the U.S.
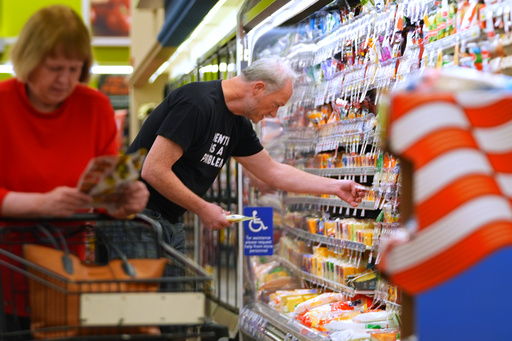
The latest updates come a week after voters across the U.S. gave Democrats a sweep of Congress in the midterm elections as stubbornly high prices on everything from gasoline to groceries squeeze households and businesses. The U.S. war with Iran that started in February slashed global oil supplies and fueled inflation that was already stubbornly high amid President Donald Trump's unpredictable tariff conflict with much of the world.
Economists, investors and policy makers are all closely watching economic indicators to get a better sense of the continued impact that the war and tariffs are having on prices, housing and employment.
Here’s a look at some of the key reports coming in the week ahead.
Inflation tightens grip on consumers and businesses
Rising prices remain a pressure point on the broader economy and the latest updates are not expected to show that has changed.
On Tuesday, the U.S. will release the consumer price index for October and economists are projecting that the rate of inflation increased to 3.9% from 3.7% in September. The index measures price changes for a wide range of products and services. The CPI has shown inflation rising at more than 3% since March, a month following the U.S. war with Iran and the big surge for energy prices that jolted gasoline prices and shipping costs.
On Friday, the U.S. will release the producer price index for October, which captures inflation before it reaches consumers. The September report showed the biggest increase since December 2022 and that data showed that rising fuel prices, particularly for diesel fuel, continue to push shipping and warehousing prices higher.
Crude prices plunged in the past week however, following U.S. midterm elections. Many believe Democrats, who routed President Donald Trump's GOP, will push to end the conflict with Iran that has sent energy prices soaring.
America's housing market is not in a good place
The housing market remains weighed down by high prices and rising interest rates. Home sales have been stagnant and the latest update on sales of previously occupied homes is expected to reflect that trend. The National Association of Realtors on Thursday will release its October report for existing home sales. Economists expect it to be mostly unchanged from September.
Home sales have been mostly hovering close to a 4-million annual pace going back to 2023, far short of the historic norm that is closer to 5.2 million. Home prices have risen on an annual basis for 39 months in a row and the average rate on the benchmark 30-year mortgage is hovering around its highest level in nearly three years. Mortgage rates will likely remain high as the Federal Reserve weighs another hike to its benchmark interest rate at its December meeting in an effort to try to cool stubbornly hot inflation.
Unemployment update after big gains in October
The U.S. on Thursday will release its weekly update on unemployment claims, which are a proxy for layoffs. Economists monitor the weekly data because they can be a sign of where the job market is headed. The latest weekly update shows that claims remain at historically low levels.
The broader job market remains resilient. U.S. employers created 165,000 new jobs in October. The jobs market has been remarkably resilient, but has shown signs of stress.
Wage growth has been slow and hasn't been keeping up with inflation, making the squeeze from rising prices even more painful for households. And while layoffs have been held largely in check, it is growing more difficult to find a job if you are let go.
Corporate earnings continue to roll out
There will be a smattering of notable corporate earnings next week that will likely provide insights into the state of artificial intelligence and data centers, as well as Hollywood.
After a brutal week in AI, CoreWeave will report quarterly earnings Tuesday. The data center company has been seen by some as more vulnerable as the costs of borrowing money rise. Its shares fell close to 20% in the past week. Cisco and Applied Materials report results on Thursday.
SkyDance posts earnings on Monday, the first since its Paramount studios closed on an $81 billion takeover of Warner Bros. Discovery, ushering in a new Hollywood giant.